
UnitedHealth earned $0.38 billion of operating profit on $113.22 billion of revenue in the quarter ended December 2025. That is 0.3 cents on each dollar, in a business that had earned between 8 and 9 cents for years. Two quarters later the figure was 7.1 cents.
So is the worst over? On the measured margin, the bottom was the December 2025 quarter, and it has not been revisited since. The stock at $376.90 is telling you it agrees, and the open question is how much of the recovery is already in the price.
My view is a qualified yes. The damage of fiscal 2025 is visible in every profit line, and two consecutive quarters of repair are now on the record, but the margin has not returned to where it was and the forward multiple assumes it will.
A year that halved the profit line
Operating income was $32.36 billion in fiscal 2023 and $32.29 billion in fiscal 2024. In fiscal 2025 it fell to $18.96 billion, a drop of 41% in one year, while revenue rose 12% to $447.6 billion. Sales grew, profit collapsed. The UnitedHealth financials page has the full statement history behind these figures.
Put as margins, the fall is easy to read. The database’s EBIT margin was 8.3% in 2021, 8.8% in 2022, 8.7% in 2023, then 6.0% in 2024 and 4.2% in 2025. For three years the ratio barely moved, which is why the stock was thought of as the one nobody argued with. Then it lost roughly half in two years.
Gross margin tells the same story from a different side: 22.3% in 2024 and 18.5% in 2025, against 24.5% in 2023. Our database does not break out the medical costs that drive this, so I read the gross margin as a proxy for how much of each premium dollar is left after paying for care and services. Whatever the specific cause, it is the cost side that moved. Revenue did not.
Earnings per share followed. Diluted EPS was $23.86 in 2023, $15.51 in 2024 and $13.23 in 2025, down 45% over two years. Net income fell from $23.14 billion to $12.8 billion.
The quarter that touched zero
The quarterly figures are where the title gets answered. Five quarters of revenue and operating profit, in dollars and as a share of sales, are in the table below.
Operating profit was $5.15 billion in the June 2025 quarter and $4.32 billion in September. Then $0.38 billion in December. Net income to common shareholders that quarter was $0.01 billion, essentially nothing on $113 billion of sales.
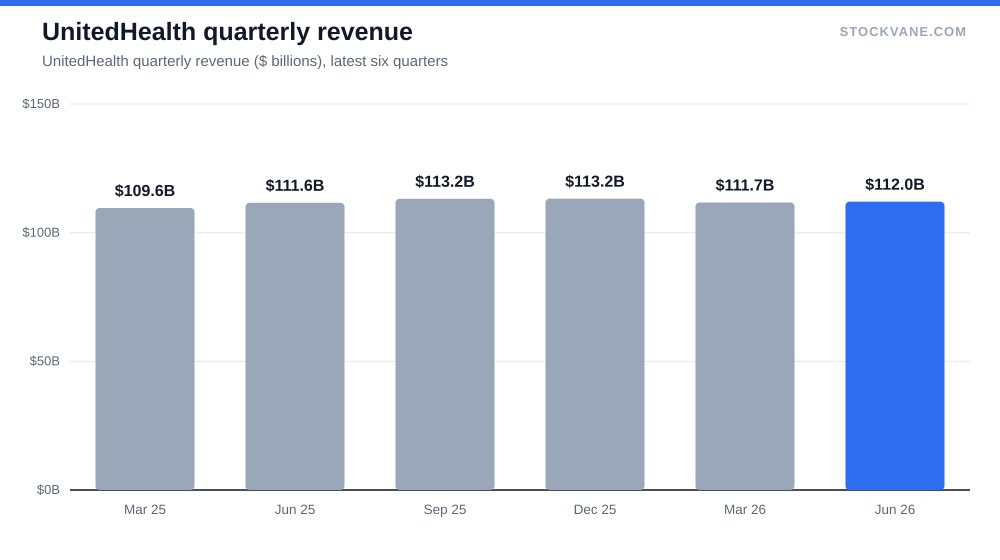
Compare the same quarter a year earlier and the pattern is starker: the March 2025 quarter earned $9.12 billion at 8.3%, and the March 2026 quarter earned $8.99 billion at 8.0%. Revenue in the later quarter was $111.72 billion, up 2% from $109.58 billion, so UnitedHealth is back to roughly the same profit on slightly more revenue, and no better than that.
| Fiscal quarter | Revenue ($B) | Operating profit ($B) | Operating margin |
|---|---|---|---|
| Q2 2025 (Jun 2025) | 111.62 | 5.15 | 4.6% |
| Q3 2025 (Sep 2025) | 113.16 | 4.32 | 3.8% |
| Q4 2025 (Dec 2025) | 113.22 | 0.38 | 0.3% |
| Q1 2026 (Mar 2026) | 111.72 | 8.99 | 8.0% |
| Q2 2026 (Jun 2026) | 112.03 | 7.99 | 7.1% |
The June 2026 quarter was a step down from March: $7.99 billion, or 7.1% of revenue, against 8.0%. I would not read that as a relapse, since quarterly margins in this business move with seasonality in claims, but it does mean the recovery is not a straight line. The average of the last two quarters, about 7.5 cents per dollar, is still roughly a seventh below the 8.7% the company earned in fiscal 2023.
One more comparison helps. Across the four quarters of fiscal 2025 the company earned $18.96 billion of operating profit, an average of $4.74 billion a quarter, and the two quarters since average $8.49 billion. That is 79% more per quarter than the fiscal 2025 average. It is also below the $9.12 billion of the March 2025 quarter, the last one before the slide started, so the gap to the old run rate is real, if narrow.
The net income line makes the same point with less noise from operating items. Net income to common shareholders was $6.28 billion in the March 2026 quarter and $5.48 billion in June. A year earlier the same two quarters produced $6.29 billion and $3.41 billion. March is a wash, and June is up by about $2.1 billion. That June comparison is the strongest single piece of evidence for recovery in the data, because it sets a repaired quarter against the first quarter of the damage.
What the stock already assumes
At $376.90, UnitedHealth is 17.9% below its 52-week high of $459 and 49% above its low of $253. It has therefore recovered about 60% of the distance from the bottom to the top of the range. The market cap is $338.3 billion.
The trailing P/E is 24.2, against a five-year average of 25.4, so the stock trades at 0.95 times its own history (46th percentile). That looks unremarkable until you remember that trailing EPS of $15.56 is depressed. The forward P/E is 18.9 on expected EPS of $19.97, which is 28% above the trailing figure. The industry average trailing P/E is 22.3, so the market is willing to pay roughly the industry rate for a company whose earnings are supposed to jump.
Low multiples on damaged earnings are a familiar trap. Our note on Alphabet as the cheapest big-tech name makes the same point about a low multiple, and our look at JPMorgan near its record high covers a large financial that sits at a much higher multiple to earnings than its own history. The full multiple history is on the UnitedHealth valuation page.
That growth is the part to test. The forward EPS of $19.97 sits above the $15.51 earned in fiscal 2024 and below the $23.86 of fiscal 2023. The consensus does not require a full return to the old margin; it requires most of one. If margin settles at 7.5% on about $448 billion of annualized revenue, operating income would be about $33.6 billion, which is roughly where fiscal 2023 and 2024 were. That is the arithmetic the price relies on.
Analysts lean that way. Of 21 covering the stock, 81% rate it a buy, the average target is $487 (29% above the price) and even the lowest, $430, is 14% higher. Our data does not show a single sell rating. I treat that as information about sentiment more than about value: a unanimous chorus has usually already been priced.
The stock’s own valuation gauges are mixed. Price-to-sales of 0.8 sits below its five-year average of 1.2, and price-to-book of 3.5 is well below the 5.0 average, at the 20th percentile. Those look cheap, but insurers trade on earnings, not on sales, so I put more weight on the P/E figures.
Where the case could break
A single condition would make me wrong: the quarterly operating margin falling back below 5% in a quarter that is not seasonally weak. The December 2025 quarter proved the business can reach zero. It also showed that a cost shock can arrive inside one quarter, so two good quarters do not yet make a trend.
The second risk is the revenue line, which has stopped growing. The last quarter’s revenue of $112.0 billion was up 0% from the year before, and the sequential change was also flat. A margin recovery on a flat top line means, as I read it, that the improvement is coming from margin repair and not from volume, and there is a ceiling on how much of that one can bank. Margin repair on flat sales resembles the pattern in Oracle’s cash-flow story only in one respect: in both cases the reported profit line is not the whole picture.
Third, the mix. In the June 2026 quarter, UnitedHealthcare accounted for $86.0 billion of the segment revenue, Optum Rx $38.3 billion and Optum Health $23.5 billion (before eliminations of roughly $41 billion, which is why the segment lines add to more than the total). The database gives no segment margins, so I cannot say which piece is repairing fastest. If you own the stock, that is the number you would want.
I am not covering litigation or regulatory outcomes here. Our data has no dated legal facts for them, and a forecast built on guesses about a settlement would be weaker than one built on the margin.
Income and momentum
The dividend was $8.95 per share over the last twelve months, a yield of 2.37%. That is a decent payout, but it is not why anyone bought UnitedHealth in 2025, and it did not protect the shares.
Our quant grade moved from B to C between the start of September and now, and short interest is only 1.7% of float. Neither is a signal on its own. Short interest that low says no one is betting seriously on a relapse, which is one more reason the price does not carry a discount for one. The average earnings-day move is 7.1%, and the last report on 2026-07-16 brought +1.2%, an unusually quiet reaction for this stock.
The margin to hold it to
The margin figure I would hold UnitedHealth to is 7% for the September 2026 quarter. If operating profit divided by revenue lands at or above that, on revenue near $112 billion (a little under $8 billion), the recovery has legs and forward EPS of $19.97 is credible. Two quarters at 8 and 7 cents show it can be done.
Below 5% and the December quarter was not a bottom but a warning, and 18.9 times forward earnings would need a lower earnings number underneath it.
Gavin Thorne has invested in U.S. stocks for six years and previously worked at a large publicly traded internet company. He writes about income-oriented strategies, including cash-secured puts, and about how he reads company data. This article reflects his personal research process and is for informational purposes only. It does not constitute investment advice.
Sources: Dividends (SEC Investor.gov glossary) (https://www.investor.gov/introduction-investing/investing-basics/glossary/dividend) · Dividends tax topic (IRS) (https://www.irs.gov/taxtopics/tc404)