
Picture a rack of the newest accelerators sitting in a warehouse, paid for and powered down, waiting on a substation that will not be finished for three years. For a growing number of data center developers that is not a hypothetical. It is why I have spent the last few weeks reading grid-operator filings instead of earnings calls.
My argument is simple. For two years the AI trade was a bet on chips, and the bet worked. The binding constraint has moved to electricity, and the cleanest way to own that is not the loudest one. The market has already started to discount the most obvious version of the trade, and that is where the opportunity, and the risk, now sits.
The number that reframes everything
Data centers used about 4.4% of US electricity in 2023, according to the Lawrence Berkeley National Laboratory report the Department of Energy released at the end of 2024. The same report projects a range of 6.7% to 12% by 2028. Even the low end is a jump of half again in five years for a load that took decades to grow to its current size.
Forecasts like this deserve suspicion at the high end, and I will come back to why. But the direction is not in doubt, and the grid was not designed for that slope. Building generation and transmission takes years even when everyone agrees on what to build.
What the grid is willing to pay
The clearest sign of scarcity is a price. PJM, the operator that covers thirteen states from Illinois to Virginia, runs an auction every year to make sure enough generating capacity will exist three years out. For the 2024/25 delivery year it cleared at about $29 per megawatt-day. For 2025/26 it cleared near $270. For 2026/27 it hit the price cap of about $329, and the 2027/28 auction cleared at a record $333.44, again at the cap.
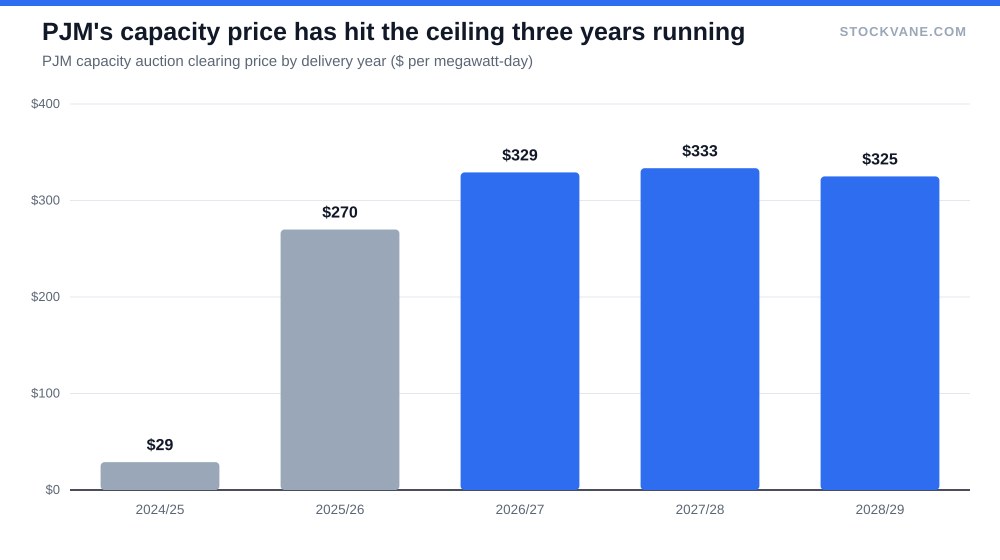
The most recent auction, for 2028/29, cleared at a cap of $325 per megawatt-day, and PJM said it procured roughly 6.8 gigawatts less than its own reserve target. The prices stopped rising only because the rules stopped them. When a market clears at the ceiling for three straight years and still comes up short of what it needs, the ceiling is doing the work that prices usually do. PJM has scheduled a one-time emergency procurement for September to close some of that gap.
The hardware queue
Then there is the equipment that turns fuel into power. GE Vernova said in July that its gas turbine backlog and slot reservations reached 116 gigawatts, up from 100 gigawatts a quarter earlier, and that it expects at least 125 gigawatts under contract by year-end. Of the 116, 53 gigawatts are firm orders and 63 are reservations, which is a way of paying to hold a place in line. Quarterly orders grew 88% to $24.2 billion and the company’s total backlog reached $176 billion.
One detail I find telling is the flow. In the quarter GE Vernova signed contracts covering about 20 gigawatts of new gas equipment, converted roughly 10 gigawatts of earlier reservations into firm orders, and shipped about 3 gigawatts. Twenty in and three out is how a queue gets longer, and it is why a reservation is a real asset and not just a promise.
A developer who decides today that it needs a gigawatt of new gas generation next to a campus is looking at a wait of years for the turbine alone. Large transformers have lead times past two years. None of this gets fixed with a bigger check, and that is what separates it from the chip shortage of 2023 and 2024. Chip supply expanded when foundries built more fabs. A turbine factory is a similar project, but it is also joined to a permitting process, a fuel supply and a transmission line, and every one of those runs on its own clock.
What the biggest buyers are telling you
The hyperscalers understood this before the market did. Microsoft agreed to a twenty-year deal that helps restart a shuttered reactor at Three Mile Island. Amazon signed a long-term power agreement with the Talen-owned Susquehanna nuclear plant in Pennsylvania, and Meta signed a twenty-year deal for output from the Clinton plant in Illinois. Google signed a development agreement for small modular reactors. When the richest companies on earth start contracting for 2028 power in 2025, they are telling you the constraint is real.
Where the money is exposed
I think about it as layers, because each has a different way of going wrong.
| Layer | Representative names | How it earns | Main risk |
|---|---|---|---|
| Merchant generation | Constellation, Vistra, Talen | Sells power into tight markets at rising prices and signs direct deals with hyperscalers | Prices are cyclical, so a demand air pocket reaches earnings fast |
| Turbines and grid equipment | GE Vernova, Siemens Energy | Multi-year backlog already booked, with pricing power on new orders | Execution and warranty costs; a backlog is only as good as delivery |
| Regulated utilities with data center load | NextEra, Southern, Dominion | Rate base grows with each connection and earns an approved return | Regulatory lag: the money is spent now and earned back over years |
| Nuclear-heavy operators | Constellation, Vistra | Carbon-free baseload is what a 24/7 data center wants | Restart and license timelines slip, and one outage is material |
The AI infrastructure guide maps who sits where in this spending wave in more detail. My own preference sits in the middle two rows. Merchant generators earn more when power is scarce, but their profits swing with prices, so you are buying a thesis and momentum together. Turbine makers and regulated utilities give you a slower, more contracted version of the same demand. GE Vernova sells into every one of these projects no matter which fuel wins, and its backlog is a number on a balance sheet, not a forecast.
Regulated utilities work differently, and the difference matters. When a utility connects a new data center it has to build substations and lines, often new generation too, and that spending goes into the rate base, where it earns an approved return that is usually somewhere around 9% to 10%. The catch is timing. The capital leaves the building in 2026 and 2027, and the return shows up in customer bills over the years after a rate case. A utility with real data center growth is therefore a slower compounder than a merchant generator in a boom, but its earnings are a contracted stream and not a bet on next winter’s power prices.
The market has already noticed
Here is the part that has changed since I first looked at this, because the shares have moved. Every name I use as an example is now below its 52-week high.
| Company | Price | From 52-week high | P/E (TTM) | Dividend yield |
|---|---|---|---|---|
| Constellation Energy (CEG) | $255 | -38% | 24.9x | 0.64% |
| GE Vernova (GEV) | $940 | -21% | 27.0x | 0.21% |
| NextEra Energy (NEE) | $80 | -17% | 18.1x | 2.96% |
| Southern Company (SO) | $86 | -13% | 20.6x | 3.48% |
| Dominion Energy (D) | $64 | -12% | 22.2x | 4.20% |
The merchant generator Constellation sits about 38% under its peak, GE Vernova about 21% under, and the regulated utilities between 12% and 17%. I will not offer a reason, because the data does not give one. It does mean that anyone who bought the theme at its high has already been asked to sit through a lot of volatility, and that the price of the boring version, the utilities at 18 to 22 times earnings with yields near 3% to 4%, has held up better than the price of the exciting one.
What would break this
Three things, and I watch all of them. The first is phantom demand. Grid operators have admitted that a large share of the load waiting in their interconnection queues is speculative or duplicated, the same project filed with several utilities at once to see which says yes first. Estimates of how much of it gets built vary widely, and some run below half. If the real buildout lands at the low end of the Berkeley range, the tightest forecasts loosen, and merchant power gets repriced well before any plant is switched off.
The second is the AI spending cycle itself. If the capital spending behind all of this slows, as I argued was a real possibility in my piece on whether this is 1999 again, the power demand curve bends down with it. Electricity is a derivative of the compute buildout, not a separate story. A hyperscaler that trims its 2027 plans by a fifth is trimming its power procurement too, and contracts that look ironclad today have exits written into them.
The third risk is political, and it is easy to miss when you are staring at margins. Capacity prices flow through to customer bills. When a grid operator’s auction quadruples the cost of reliability in a year, regulators and governors notice, and the response is rarely to let the price run. Price caps exist for a reason. A regulated utility that keeps asking for approval to spend more is exposed to the same pressure from the other side, because the customers who pay the return are also voters.
I should be honest about what I do not know. I cannot tell you how much of the queued demand is real, and I cannot tell you whether the current prices for capacity are close to a peak. What I can say is that both questions have observable answers within a few quarters, in the auction results and in turbine orders.
Why I would own the boring version
The shape of the next few years looks clear to me even if the timing does not. The chip shortage got solved the way shortages usually do, with more factories. The power shortage cannot be solved that quickly, because nobody can permit, finance and build a plant or a transmission line in eighteen months. That mismatch is where the pricing power lives.
If I had to choose, I would take the contracted version: the regulated utilities with genuine data center growth, and the equipment makers with backlogs already on the books. They give up some upside in a boom and lose far less if the buildout disappoints. In a market this unsure about the pace of the AI buildout, I would rather own the parts that get paid either way.
Financial disclaimer: The content on StockVane is for educational and informational purposes only and should not be construed as professional financial advice. Stock market investing involves risk of loss.
Sources: Dividends (SEC Investor.gov glossary) (https://www.investor.gov/introduction-investing/investing-basics/glossary/dividend) · Dividends tax topic (IRS) (https://www.irs.gov/taxtopics/tc404)