
Four quarters of Alphabet earnings per share add up to $19.91. Its last full fiscal year, 2025, came in at $10.81. Same company, and the trailing figure is up 84% after two more quarters of reporting.
That jump is the reason Alphabet screens as the cheapest of the five big US technology names. At $349.54 a share the snapshot P/E is 17.5, against 20.4 for Amazon, 25.1 for Meta, 27.5 for Microsoft and 38.5 for Apple. The title of this post is true on that measure. My argument is that it is a weaker truth than it looks, because the discount depends on a net income line that the business itself did not produce.
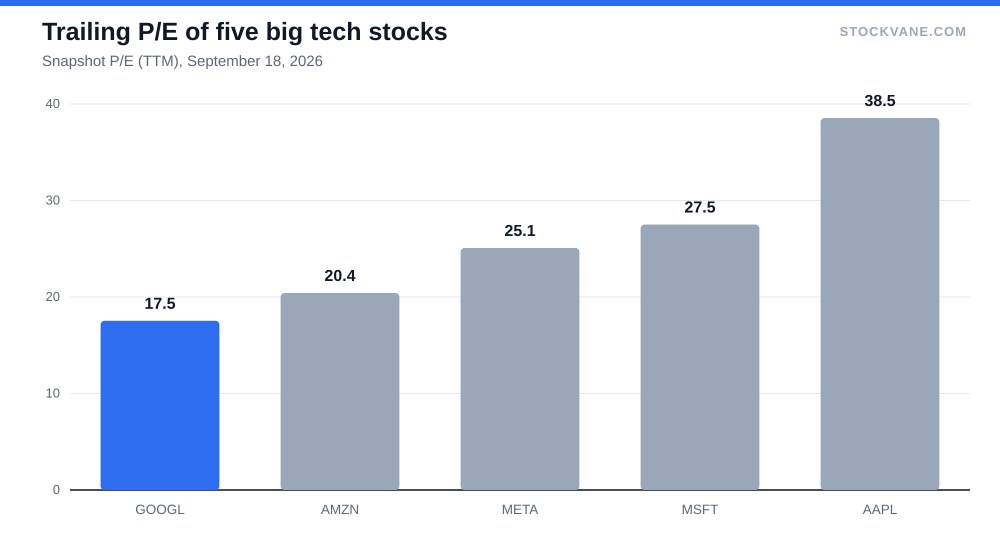
Where the cheapness comes from
The Alphabet valuation page uses the same trailing figure. Divide the price by fiscal 2025 EPS of $10.81 instead and the multiple is 32.3, which drops Alphabet to third of five behind Microsoft at 27.5 and Meta at 28.3. Nothing about the shares changed between the two calculations. Only the earnings window did. Six months of newer results moved a large, fast-growing company from third-cheapest to cheapest.
So what moved the window? The quarterly income statements answer that. Net profit in the June 2026 quarter was $112.2 billion. Operating profit that quarter was $40.8 billion. The other $71 billion or so did not come from selling ads, cloud capacity or subscriptions. The database does not itemize it, and I will not guess at the source with any confidence. What I can say is that in the four quarters ending June, net income totals $244.2 billion while operating profit totals $147.6 billion, a gap of $96.6 billion in the wrong direction for anyone treating that net figure as a repeatable earnings base.
One comparison makes the point sharper. Microsoft’s trailing net income is $21.5 billion below its operating profit, which is the ordinary pattern once tax is paid. Meta is $18.8 billion below. Apple is $25.9 billion below. Amazon is the only other name above the line, by $41.6 billion, and it shows the same pattern, though at a smaller scale.
The same five names, priced on operating profit
Operating profit is a cruder measure than net income, since it ignores interest, investment gains and tax. That crudeness is the point here. It strips out the line that flatters Alphabet and leaves the machinery. Dividing each company’s market value by its trailing four-quarter operating profit gives a different order.
| Stock | Trailing P/E (snapshot) | Market value / trailing operating profit | Operating margin | Net income minus operating profit ($B) |
|---|---|---|---|---|
| Meta Platforms (META) | 25.1 | 19.5 | 38.1% | -18.8 |
| Microsoft (MSFT) | 27.5 | 23.6 | 46.8% | -21.5 |
| Alphabet (GOOGL) | 17.5 | 29.0 | 33.1% | +96.6 |
| Amazon (AMZN) | 20.4 | 29.2 | 12.1% | +41.6 |
| Apple (AAPL) | 38.5 | 31.7 | 33.2% | -25.9 |
Meta comes out cheapest at 19.5 times operating profit, Microsoft next at 23.6. Alphabet sits third at 29.0, a hair ahead of Amazon at 29.2 and Apple at 31.7. Alphabet’s own headline discount is real in the sense that the arithmetic works. On the profit its operations generated, though, it costs more than Microsoft and Meta, about 1.2 times Microsoft’s multiple.
I do not read that as a reason to sell. I read it as a reason to stop calling the stock a bargain by default. A bargain implies the market is missing something. Here the market is looking at the same operating profit as everyone else and applying a higher multiple than it does to two of its rivals.
What the operating line does say
The business itself is in good shape. Revenue in the June quarter was $119.8 billion, up 24.2% from the year before. Operating profit rose 30.4% on that, to $40.8 billion, so margins are widening and not just holding. Over the trailing four quarters Alphabet’s operating margin is 33.1%, about the same as Apple’s 33.2% and well behind Microsoft’s 46.8% and Meta’s 38.1%.
Growth has also sped up. Revenue growth was 12.0% in the March 2025 quarter, 13.8% in June 2025, 15.9% in the September quarter, 18.0% in December, 21.8% in March 2026 and 24.2% in June. Six quarters, and every one faster than the last. A company compounding revenue at that pace on a $446 billion trailing base deserves a real multiple, and 29 times operating profit does not look punitive.
Mix matters too. Google Services brought in $94.5 billion of the quarter’s revenue, or 78.9%. Google Cloud brought in $24.8 billion, 20.7%. Other Bets and hedging together are under one percent. The older framing, in which Search advertising is the whole story, is out of date. One fifth of revenue now comes from a segment selling compute and software to other companies. That is also the segment that competes head-on with the one I covered in the Microsoft forecast.
Amazon shows why the operating view matters beyond one stock. Its snapshot P/E is 20.4, second-lowest of the five, and its market value is 29.2 times operating profit. The distance between those two numbers is $41.6 billion of net income above operating profit again. Two of the five cheapest-looking stocks on earnings are the two with the largest positive gaps, and I do not think that overlap is an accident of the sample. It suggests the trailing P/E screen is currently picking up whatever sits beneath operating profit, and only secondarily the value of the businesses. Amazon also earns an operating margin of 12.1%, well under a third of Microsoft’s, so it is a different kind of company from the other four. Alphabet at 33.1% is the only one that combines a high margin with a low headline multiple, which is exactly why the gap deserves scrutiny.
The cash the multiple has to be paid from
Alphabet generated $164.7 billion of operating cash flow in fiscal 2025, up from $125.3 billion in 2024. Free cash flow was $73.3 billion, barely above the $72.8 billion of the year before. The difference, roughly $91 billion, went to capital spending, and that is the number to hold against every optimistic multiple in this post.
At a market value of $4.27 trillion, fiscal 2025 free cash flow is a 1.7% yield. Dividends took $10.05 billion of it. That leaves little for a share price that has already climbed 48.6% from its 52-week low of $235.23. The stock is 14.4% below its 52-week high of $408.10, so it has given back some ground, but not enough to change the cash arithmetic.
Meta is the useful comparison. Its stock fell after a quarter of heavy AI spending, which I wrote about in Meta Spent $19 Billion in One Quarter on AI. Alphabet has spent on the same scale and been treated less harshly. Its shares rose 10.0% on the April 29 report and fell 7.1% on July 22.
Two reports, two opposite reactions. No consistent rule about what investors are paying for.
The counter-case, taken seriously
One fair objection first.
The strongest argument against everything above is that operating profit undercounts what Alphabet owns. If a large part of that $96.6 billion gap reflects gains on assets that can be sold or marked again, the market may be right to give it some credit. A holder who takes the net income seriously could reasonably say the 17.5 multiple is closer to the truth than 29.
I would not dismiss that. I would only ask what the credit is worth if the gains are not repeated. The June quarter’s net profit rose 297.9% from the year before, while operating profit rose 30.4%. Those two growth rates cannot both describe the same recurring business. One of them is the business, and the other includes something else.
What I am not covering here is the antitrust question, which sits outside what the database can measure, and anything about how fast search queries are changing. Both matter, and neither can be tested against the figures I have. Readers who want the broader context on the other names can start with the Apple piece, and the list of tech stocks worth buying cautiously in Q4 2026 frames how I think about entry points.
What the next net income line has to show
The test is simple. Alphabet’s next quarterly report should show operating profit near or above $40 billion, which would confirm that the $40.8 billion in June was the base and not a peak. It should also show net income much closer to operating profit than $112.2 billion is to $40.8 billion. If net income falls back toward $45 billion or $50 billion, the trailing P/E moves from 17.5 toward the high twenties and the cheapest-in-Big-Tech label disappears without a single share trading differently.
If operating profit slips below $38 billion, I would treat 29 times as too much to pay. The last four quarters ran $31.2 billion, $35.9 billion, $39.7 billion and $40.8 billion, so a print under $38 billion would mean the climb had stalled after only two quarters at the higher level.
Until then the label is the market’s shorthand. The number underneath is more expensive than it looks.
Gavin Thorne has invested in U.S. stocks for six years and previously worked at a large publicly traded internet company. He writes about income-oriented strategies, including cash-secured puts, and about how he reads company data. This article reflects his personal research process and is for informational purposes only. It does not constitute investment advice.
Sources: Dividends (SEC Investor.gov glossary) (https://www.investor.gov/introduction-investing/investing-basics/glossary/dividend) · Dividends tax topic (IRS) (https://www.irs.gov/taxtopics/tc404)